Renting Out a Garage Condo: Rates, Rules & Real Returns
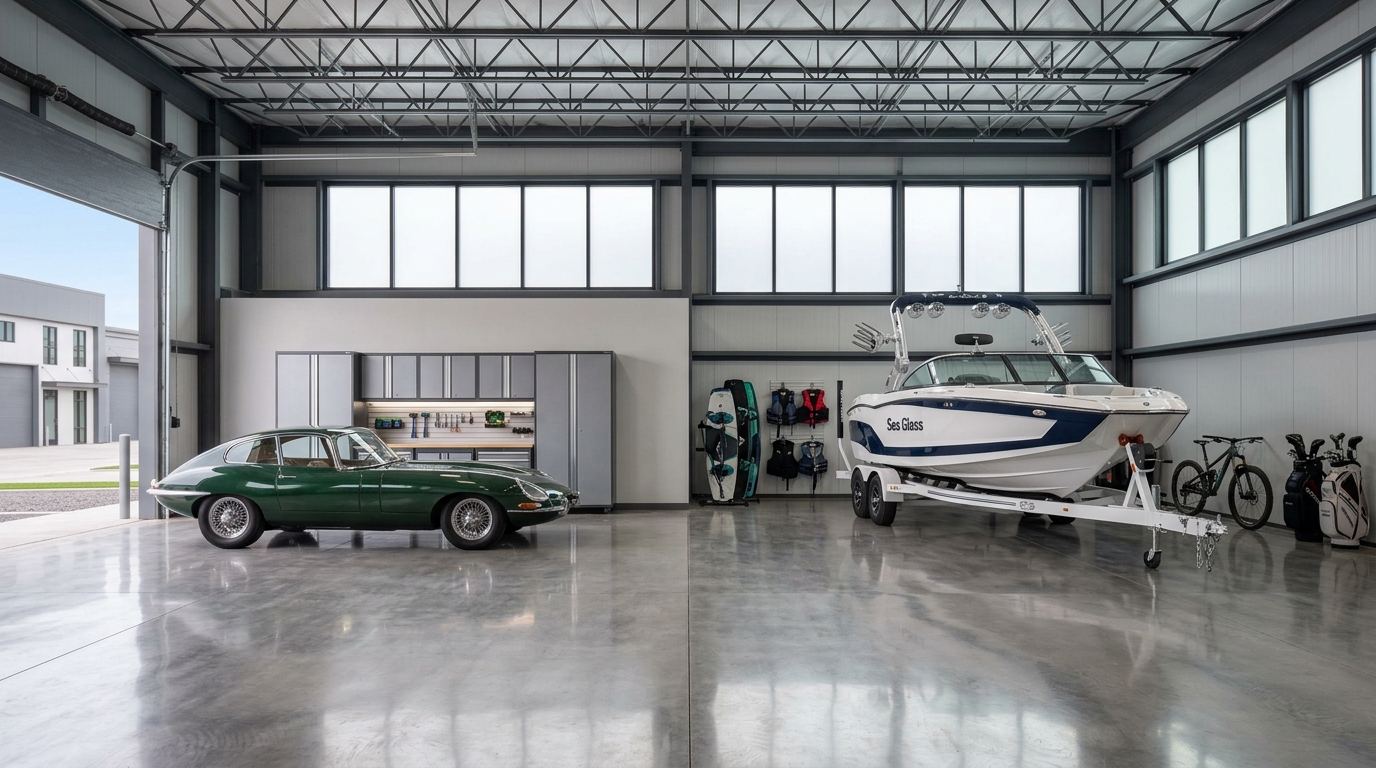
Garage condos occupy an unusual corner of real estate: they are deeded property you can lease like a commercial unit, but the tenant pool behaves more like a luxury consumer market. Collectors need climate-controlled space for cars they will not park outside. Small businesses need clean, secure bays without signing a five-year industrial lease. RV and boat owners face HOA rules at home that ban driveway storage. All of that demand funnels toward a product that most metros have very little of, which is why well-located garage condos routinely lease quickly and hold their rates. This guide covers what garage condos actually rent for in 2026, the association rules that decide whether you can rent at all, the underwriting math, tenant screening, lease terms, taxes, risks, and the question every owner eventually asks: rent it or sell it?
Why Garage Condos Rent Well
The core dynamic is scarce supply against sticky demand. A storage tenant with a $40,000 boat or a six-figure car collection does not churn the way an apartment tenant does. Moving a collection is a project, and the alternatives, public storage, a warehouse lease, a friend’s barn, are all worse on security, climate control, or convenience. Once a serious tenant settles into a garage condo, multi-year stays are common.
Demand comes from several distinct pools, and understanding which pool dominates your market tells you how to price:
- Car collectors and enthusiasts who want secure, conditioned space plus room to wrench or hang out.
- RV and boat owners priced out of covered storage or banned from home storage by their residential HOA.
- Small businesses, detailers, contractors, e-commerce sellers, mobile service operators, who need a clean bay with power and a bathroom nearby.
- Downsizers and estates holding vehicles or household goods between life stages.
If your community sits near a motorsports track, a marina, or a wealthy suburb with strict residential HOAs, you are usually renting to the first two groups at premium rates. Near industrial corridors, the business tenant often sets the market.
What Garage Condos Rent For in 2026
There is no national MLS for garage condo leases, so rates are best understood as bands by unit type and market tier rather than a single number. Based on asking rents across the communities in our national directory and typical market ranges, here is how 2026 pricing breaks out:
| Unit type | Typical size | Market profile | Typical monthly rent |
|---|---|---|---|
| Basic bay, unfinished | 400–700 sq ft | Secondary markets, older stock, no climate control | A few hundred dollars ($300–$700) |
| Mid-tier finished unit | 700–1,200 sq ft | Epoxy floor, insulated, power, metro-adjacent | $800–$1,500 |
| Premium large unit | 1,200–2,500+ sq ft | Climate control, mezzanine, clubhouse community, major metro | $1,500–$2,500+ |
One concrete data point from the directory: a garage condo community in Spokane, Washington leases units starting around $1,250 per month, a useful reminder that strong lease rates are not limited to Miami or Scottsdale. A mid-size metro with thin supply can out-earn a big metro with three competing developments. Before you set a price, check every comparable community within a 30-minute drive on our map, call them as a prospective tenant, and note waitlists. A waitlist at a competitor is your green light to price at the top of the band.
Read the Declaration Before You Do Anything Else
The single biggest mistake new garage condo landlords make is listing the unit before reading the condominium declaration and rules. These are recorded documents that bind you regardless of what the sales agent said, and leasing provisions vary enormously between communities. Look specifically for:
- Leasing permission and caps. Some declarations allow unrestricted leasing; others cap the percentage of units that may be rented at any time, require board approval of each lease, or impose a waiting period (often one to two years of ownership) before you may lease at all.
- Minimum lease terms. Many associations prohibit short-term rentals outright and set a minimum lease of six or twelve months. Do not plan an Airbnb-style “garage by the weekend” business inside a condo association without written confirmation it is allowed, it almost never is.
- Use restrictions that bind your tenant. Prohibitions on habitation (nobody sleeps in the unit), on certain commercial activities (auto repair for the public, paint and body work, anything generating customer traffic), on hazardous materials storage, and on noise or operating hours. Your lease must pass these through to the tenant, because the association will come after you, the owner, for violations.
- Tenant registration and amenity access. Clubhouse communities often require tenant registration, background acknowledgment, and sometimes an amenity fee before a tenant can use common areas.
- Fines and enforcement. Understand the fine schedule. If your tenant runs an unapproved business out of the bay, those fines land on your ledger.
If anything is ambiguous, get a written interpretation from the board or management company before signing a tenant. A one-paragraph email saves a four-figure dispute.
The Underwriting Math: A Worked Example
Treat the unit like the small commercial asset it is. Here is a representative example for a mid-tier finished unit in a healthy market, your numbers will differ, but the structure will not:
- Gross rent: $1,200/month
- HOA/association dues: $250/month
- Property taxes: $200/month (varies widely by state and assessed value)
- Insurance (landlord policy on the unit interior and liability): $75/month
- Maintenance and vacancy reserve: $100/month (door springs, openers, epoxy touch-ups, the occasional vacant month)
- Net cash flow before debt service: $575/month, roughly 48% of gross
On a unit purchased for $180,000 in cash, $575 per month is $6,900 per year, roughly a 3.8% unlevered cash yield before any appreciation. Add a mortgage and the cash-on-cash math changes: with financing (see our guide to financing a garage condo, these are typically commercial-style loans with larger down payments and shorter amortizations), the debt service on a mid-tier unit can consume most of the net cash flow in the early years. Many garage condo landlords are effectively break-even on cash flow while the tenant pays down the loan and the asset appreciates. That is a legitimate strategy, but go in knowing it, do not expect residential-rental cash-on-cash returns from a leveraged garage condo in year one.
Two levers improve the math meaningfully: buying in a market where rents are high relative to purchase prices (often secondary metros with thin supply), and light value-add, an unfinished bay that rents for $700 can often rent for $1,000+ after epoxy, insulation, and a mini-split costing $10,000–$15,000. Our build-out guide covers which improvements pay.
Finding and Screening Tenants
Garage condo tenants do not browse apartment sites. The channels that work:
- Enthusiast channels: local car club forums and Facebook groups, Cars & Coffee flyers, marque-specific clubs, track-day communities.
- Marketplace listings: Facebook Marketplace and Craigslist still produce, especially for RV/boat storage demand.
- Commercial listing sites: for business tenants, small-bay industrial listings reach contractors and operators who would never search “car condo.”
- The community itself: tell the association manager and your neighbors you have a unit available. Existing owners frequently want a second bay, and they are pre-screened by definition.
- Directory exposure: if your community is not listed, adding it to the directory puts it in front of people actively searching for garage space in your metro.
Screen like a commercial landlord. For individuals: credit check, verified income or assets, and a conversation about exactly what they intend to store and do in the unit. For business tenants: the entity’s standing, a personal guarantee from the principal, proof of commercial general liability insurance, and a hard look at whether the business activity is permitted by the declaration and local zoning. The best screening question is simple: “Walk me through a typical Saturday in the unit.” The answer tells you whether you are renting to a collector who visits twice a month or a detailer planning a seven-day-a-week operation.
Lease Terms That Matter
Use a written lease, ideally reviewed by a local attorney, because a garage condo lease is closer to a small commercial lease than a residential one, and residential tenant-protection statutes may or may not apply depending on your state and the use. Key provisions:
Insurance
Require the tenant to carry their own coverage: renter’s or inland-marine coverage on stored vehicles and property, and commercial general liability (often $1M per occurrence) for any business use, with you and the association named as additional insureds. State plainly in the lease that your policy does not cover their property. Then tell your own insurer the unit is tenant-occupied, an owner-occupied policy can deny claims on a rented unit.
Use restrictions
Pass through every association restriction verbatim: no habitation, no subleasing, no hazardous materials beyond normal automotive quantities, no public-facing business traffic, compliance with all association rules as amended. Add a clause making association fines caused by the tenant reimbursable by the tenant, with violation a default trigger.
Utilities and operations
Separately metered power is cleanest, the tenant opens their own account. If utilities run through the association or your meter, either build an allowance into the rent with an overage clause or bill back actuals. Address climate-control setpoints in writing if you pay for conditioning: a tenant running a 68°F workshop all summer in Florida on your meter will erase your margin. Cover door and opener maintenance responsibility, who holds codes and fobs, and your right of entry with notice.
The Tax Angle
Rental income from a garage condo is reportable, but the deductions are substantial: association dues, property taxes, insurance, repairs, management, and depreciation. Because the structure is non-residential real property, it is generally depreciated over a longer schedule than residential rentals, and some interior improvements may qualify for faster treatment. If you use the unit partly yourself and rent it partly, expense allocation gets complicated quickly. None of this is tax advice, garage condos sit in enough of a gray zone (commercial condo, mixed personal/rental use, possible business use) that a CPA who handles real estate is worth the fee in year one.
The Risks
Be clear-eyed about what can go wrong:
- Rule changes. Associations can amend leasing rules. A community that allows rentals today can impose caps or minimum-hold periods tomorrow, usually with grandfathering, but not always on your preferred terms.
- The wrong tenant. An unauthorized repair business, fluid spills on common drives, or a tenant living in the unit can generate fines, insurance problems, and a hostile board. Eviction of a commercial-style tenant is usually faster than residential eviction, but it is never free.
- Vacancy concentration. You have one unit and one tenant. A single vacancy is 100% vacancy. The reserve line in your underwriting is not optional.
- Special assessments. Roof, paving, and fire-system assessments hit landlords and owner-occupants alike, and rent does not automatically rise to cover them.
- Market supply. A new 100-unit development opening two miles away can reset rents in a thin market. Know the construction pipeline before you buy for income.
When Renting Beats Selling
Owners usually face this decision after a move, an estate event, or simply outgrowing the unit. Renting tends to win when: the unit is in a supply-constrained market with visible waitlists; your basis is low and selling would trigger a large taxable gain; the association is well-run with healthy reserves (so you are not holding through an assessment cycle); and the local market has appreciated strongly and still has demand tailwinds, as covered in our investment analysis. Selling tends to win when: the declaration makes leasing painful or capped; dues and taxes have risen to where net yield is thin; a wave of new supply is under construction nearby; or you simply do not want a second small business. A useful rule of thumb: if projected net cash flow is under 3% of the unit’s current market value and you have no strong appreciation thesis, the sale proceeds probably work harder elsewhere. If you are leaning toward selling, our buyer-demand overview shows where the deepest buyer pools are.
Bottom Line
A garage condo can be a low-drama income asset: durable tenants, minimal turnover cost, no toilets at 2 a.m. unless you installed one. The winners read the declaration first, underwrite honestly including dues, taxes, insurance, and reserves, screen tenants like a commercial landlord, and paper the lease properly. Start by checking supply and comparable communities in your market on the directory map, and if your community is not yet listed, list it, visibility is free demand.
Frequently asked questions
How much does a garage condo rent for?
Depending on market, size, and finish level, garage condo leases commonly run from a few hundred dollars a month for basic units to $1,000–$2,500+ for large finished units in premium markets. Local comparables matter more than national averages.
Can my HOA stop me from renting my garage condo?
Yes — the condo declaration governs. Some associations allow leasing freely, some require minimum lease terms or board approval, and some prohibit commercial activity by tenants. Read the declaration before you buy with rental plans.
Is garage condo rental income passive?
Mostly. With one tenant, no plumbing in many units, and the association maintaining the shell, garage condos are among the lowest-touch rentals in real estate — but you still handle leasing, insurance, and the occasional tenant issue.