Garage Condo vs. Storage Unit: The Real 10-Year Cost Comparison
Every garage condo buyer runs the same mental math at some point: “Why would I spend $150,000 to $400,000 buying a garage when I can rent storage for a few hundred a month?” It is the right question, and the honest answer depends on your time horizon, what you are storing, and whether you value the space as a place or just as cubic feet. This article builds the full 10-year cost model, rent versus own, with real numbers, then layers in the part most comparisons skip: equity, appreciation, control, and what the space actually lets you do. By the end you will know which side of the ledger you belong on, and when a hybrid approach beats both.
Two Different Products Wearing the Same Label
First, be precise about what we are comparing, because “storage” spans three very different products:
- Traditional self-storage: a 10x20 or 10x30 drive-up unit, roughly $150–$500/month depending on market and climate control. No power at the outlet for you, no working on vehicles, restricted hours, shared drives.
- Premium vehicle storage: dedicated car storage facilities with climate control, battery tending, and sometimes detailing, commonly $300–$1,000+ per vehicle per month in major metros. Your car is stored; you generally are not welcome to hang out.
- Concierge/club storage: white-glove collection management in luxury facilities, frequently $1,000–$2,000+ per month for multi-car arrangements, with transport, exercise drives, and full service.
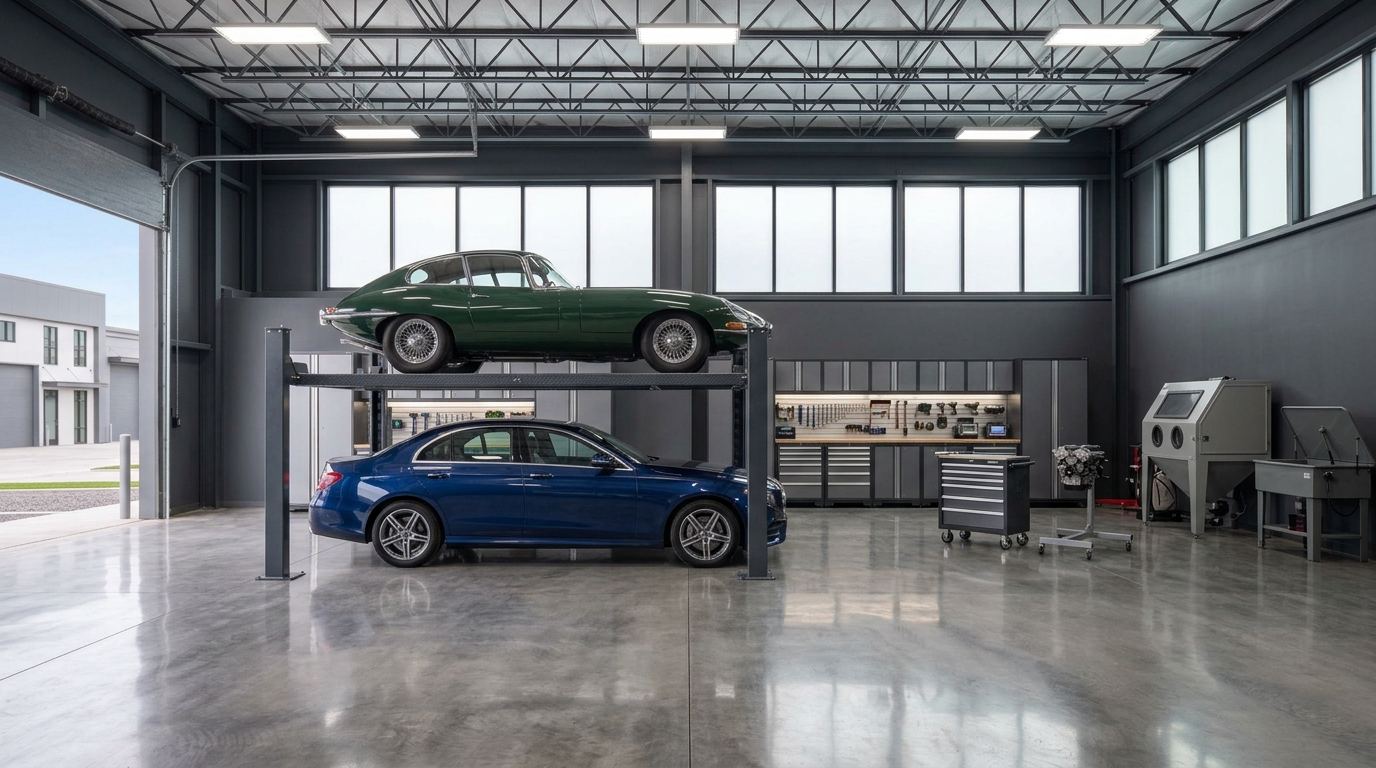
A garage condo is none of these. It is deeded real estate, your own building envelope, typically 600–2,500+ square feet, that you can finish, condition, work in, and sell. If you are not sure of the basics, start with what a car condo actually is and the full cost of ownership guide, then come back for the math.
The 10-Year Cost Model
Here is the model, kept deliberately simple and conservative. For renting, we take three realistic scenarios. For owning, we assume a $200,000 mid-tier garage condo purchased with cash (we will handle financing separately), with ownership carry of roughly $550/month: association dues (~$250), property taxes (~$200), and insurance plus maintenance reserve (~$100). Your numbers will vary by state and community; the structure holds.
| Scenario | Monthly cost | 10-year outlay | Asset at year 10 | Net 10-year position |
|---|---|---|---|---|
| Basic self-storage (climate-controlled large unit) | $500 | $60,000 | $0 | −$60,000 |
| Premium vehicle storage (2–3 cars) | $1,000 | $120,000 | $0 | −$120,000 |
| Concierge collection storage | $2,000 | $240,000 | $0 | −$240,000 |
| Own: $200K garage condo, cash | ~$550 carry | $200,000 purchase + $66,000 carry = $266,000 | Unit at market value | Depends on resale value (see below) |
Three honest caveats on the model. First, storage rents rise; we held them flat, which flatters renting. Second, ownership carry also rises (dues and taxes creep), and we held that flat too, call it a wash. Third, we excluded transaction costs on the condo (closing costs buying, commission selling), which typically total several percent of value round-trip; fold those in when you run your own numbers.
Read the chart carefully: the ownership bar is carry cost only, because the $200,000 purchase is not consumed, it is converted into an asset you still hold at year 10. That is the entire argument in one sentence. The renter’s $60,000 to $240,000 is gone. The owner’s $66,000 of carry is gone too, but the $200,000 came back as a building, worth whatever the market says at exit.
The Equity Side: What Does the Building Do Over 10 Years?
This is where the comparison stops being hypothetical. Garage condos in strong markets have appreciated meaningfully: in Florida, recorded sales data show the median garage condo resale price rose roughly 87% from 2021 to 2026 per county records, a five-year run driven by thin supply, migration, and the asset class going mainstream. That pace is not a projection, five-year windows that strong are unusual in any real estate class, and some markets will be flat or down over a given decade. But the structural case for the asset holding value is solid: construction costs have risen, land near wealthy metros is scarce, and demand from collectors, RV owners, and small businesses keeps broadening. See our deeper dive on whether garage condos are a good investment.
Run the year-10 math under three sober scenarios for the $200,000 cash buyer with $266,000 total outlay:
- Flat market: unit sells for $200,000. Net 10-year cost: ~$66,000 plus transaction costs, already cheaper than premium storage and roughly even with basic self-storage, for a vastly better product.
- Modest appreciation (2–3%/yr): unit sells in the $245,000–$270,000 range. Net 10-year cost approaches zero; you stored your collection for a decade essentially for free.
- Strong market: appreciation exceeds total carry and the decade is cash-positive, which is what many 2015–2025 buyers in Florida, Arizona, and Texas actually experienced.
Financing shifts the cash-flow picture (higher monthly outlay, smaller upfront check) without changing the underlying logic; our financing guide walks through typical structures. And there is a third option storage units cannot offer at all: the owner who leases the unit out when life changes, covered in our guide to renting out a garage condo, converting the asset into income instead of selling.
Beyond Money: Control, Lifestyle, and Business Use
Control
A storage operator can raise your rent at renewal, every renter has lived the $89 teaser rate that becomes $240 by year two, change access hours, sell the facility, or terminate your tenancy. An owner faces association dues increases and rules, but nobody can price you out of your own deeded unit or hand your space to someone else. For anyone storing irreplaceable vehicles, that certainty has real value.
Lifestyle
This is the gap no spreadsheet captures. In a self-storage unit you may not wrench on a car, run a compressor, install a lift, or spend a Saturday with friends and a TV on. In your own garage condo you can do all of it: epoxy floors, two-post lift, mezzanine lounge, mini-split climate control, see our build-out guide for what adds value. Many communities are social ecosystems with clubhouses and car events. You are not buying cubic feet; you are buying a third place that happens to hold your cars. Concierge storage offers lounge amenities too, but you are a member paying dues forever, not an owner.
Business use
Storage units broadly prohibit commercial activity and occupancy. Garage condos, subject to each association’s declaration, often permit quiet business uses: a detailer’s private studio, an e-commerce inventory hub, a contractor’s base. If your space need is partly business, ownership may also carry tax treatment a storage receipt never will, depreciation and expense deductions on a business-use asset (confirm specifics with a CPA).
When Renting Storage Wins
Ownership is not the universal answer. Renting is the right call when:
- Your horizon is short. Under roughly three years, transaction costs and market risk usually eat the ownership advantage. Storing a car during a two-year relocation? Rent.
- You store one ordinary vehicle. A $300/month unit for a single car is $3,600 a year; buying 1,000 square feet to hold one Miata is capital allocation by emotion.
- Capital is better deployed elsewhere. If $200,000 belongs in your business or portfolio, renting keeps it there.
- Your market has no inventory. Garage condos exist in limited supply; check your state and the map. No community within reasonable distance ends the debate.
- You want zero obligations. No dues, no board, no assessments, no resale process. Convenience has a price; some people are happy paying it.
Break-Even Intuition: Years 4 to 7
Here is the heuristic the full model keeps producing. Compare ownership carry (~$550–$700/month on a mid-tier unit) against the rent you would otherwise pay. Against premium storage at $1,000–$1,500/month, you save $400–$900 every month as an owner before any appreciation; against concierge rates the gap is wider still. Those monthly savings grind away at the transaction costs and the opportunity cost on your capital, and in most realistic scenarios, flat-to-modest appreciation, typical dues and taxes, the ownership position pulls ahead of renting somewhere between year 4 and year 7. The higher your rental alternative and the stronger your market, the earlier the crossover; a basic $300/month self-storage user comparing against a premium condo purchase may never cross over on dollars alone, and is buying lifestyle, which is a legitimate purchase, just a different one. The practical rule: planning to hold five or more years and currently paying four figures monthly for storage, ownership almost certainly wins. Under three years, or under $500/month in storage spend with no desire to use the space, renting wins.
Hybrid Strategies
The rent-versus-own framing hides a few smart middle paths used by experienced owners:
- Buy your core, rent the overflow. Own a right-sized unit for the permanent collection and daily use; lease a cheap storage unit for seasonal overflow instead of overbuying square footage you need two months a year.
- Buy one, lease a second bay. In many communities, owners lease additional bays from neighbors. You get expansion flexibility without a second purchase, and when you no longer need it, you walk away at lease end.
- Rent first, then buy in the same community. Leasing for a year inside a community you might buy into is the best due diligence available: you learn the board, the dues trajectory, the neighbors, and the real demand before committing capital. Several of the communities in our directory have both rental and resale availability, start with what’s for sale near you.
- Buy more than you need, lease the extra. A larger unit or a second unit leased out can offset most of your own carry, effectively storing your collection at your tenant’s expense.
Bottom Line
Over ten years, a storage renter at $500 to $2,000 a month spends $60,000 to $240,000 and owns nothing. A garage condo owner spends comparable or less in true carry, ends the decade holding a deeded asset, in Florida’s case one whose median resale rose roughly 87% from 2021 to 2026 per county records, and gets a dramatically better product the whole way: control, climate, lifts, lounges, community, and optionality to lease or sell. Renting wins on short horizons, single ordinary vehicles, and capital constraints. For everyone storing serious vehicles with a five-year-plus horizon, the math has a clear favorite. See what exists in your market on the national map, and if you already own in a community we have not listed, add it to the directory.
Frequently asked questions
Is it cheaper to rent storage or buy a garage condo?
Over a short horizon, renting is cheaper. Over 5–10+ years, ownership often wins for anyone storing valuable vehicles long-term: rent money is gone forever, while a deeded unit builds equity and has historically appreciated in strong markets.
What does climate-controlled car storage cost per month?
Enclosed, climate-controlled vehicle storage commonly runs $250–$700+ per vehicle per month in major metros, and premium collector storage with concierge service can run far higher.
Can I write off a garage condo?
If the unit is used for business purposes, owners may be able to depreciate it and deduct expenses — a benefit renters never get. Rules are situation-specific, so confirm with your accountant.